Access to capital can open doors for your business, but what you do before and after receiving the money determines whether it becomes an opportunity for growth or another financial burden.
For many entrepreneurs, getting a business loan feels like the breakthrough they have been waiting for. You have been struggling to increase inventory, purchase equipment, fulfil larger orders, or keep up with business expenses. Then, finally, the funding comes through.
It is a reason to be excited.
But there is something every business owner needs to understand: receiving a loan does not automatically solve your business problems. It gives you additional resources to work with, and how you manage those resources matters.
A loan can help you expand, but it can also become a financial burden if your business is not prepared to handle it.
And there is another side to the conversation. Lending institutions do not simply create money to distribute. They have financial obligations, operating costs, and other borrowers depending on the repayment of funds. When you take a loan, you are entering a financial agreement that requires responsibility from both sides.
So, how do you make sure your loan works for your business rather than against it?
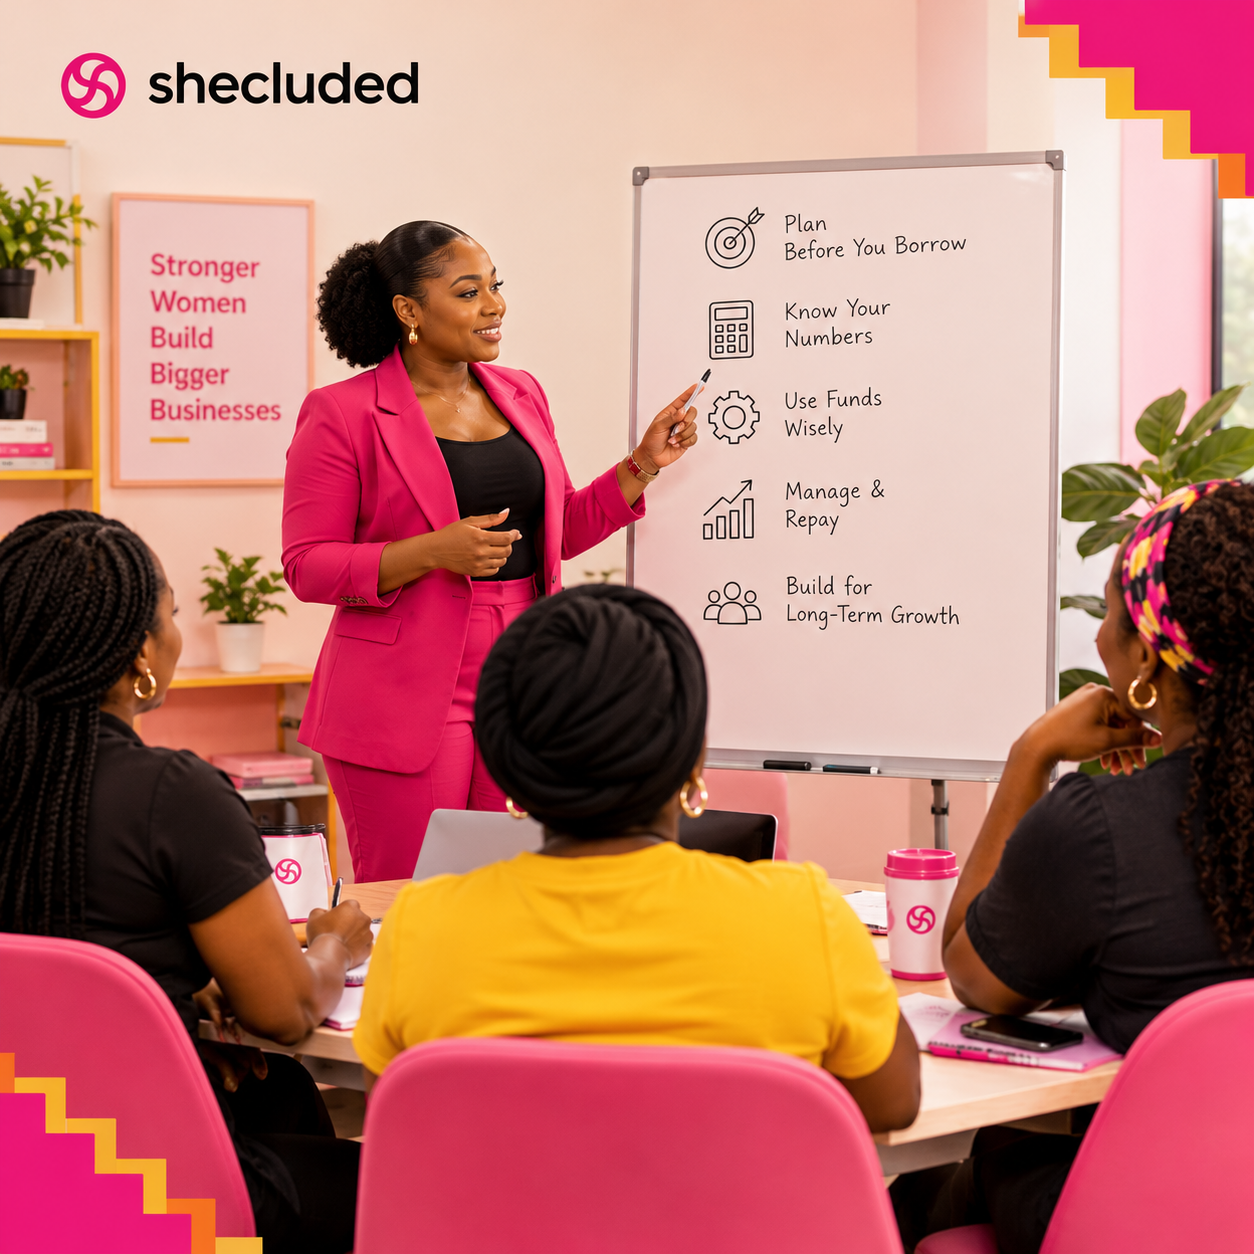
Before You Borrow, Understand Your Business
One of the biggest mistakes an entrepreneur can make is applying for a loan without understanding exactly what the business needs the money for.
How much do you need? What will the money be used for? How will that investment improve your business? And how will you repay the loan?
These questions should have clear answers before you borrow.
If you need money to purchase more inventory, estimate how much you can realistically sell and the profit you expect to make. If you are buying equipment, consider how it will improve production, reduce costs, or increase your capacity.
Avoid borrowing simply because funding is available. The amount you qualify for is not necessarily the amount your business needs.
Know Your Numbers and Your Repayment Capacity
Before taking a loan, understand your revenue, expenses, profit, existing debts, and cash flow.
A business may generate impressive sales and still struggle to meet its financial obligations because most of its money is tied up in stock, unpaid customer invoices, or operating expenses.
Look beyond how much money enters your business. Consider how much remains after your expenses and whether that amount can comfortably accommodate loan repayments.
Also, understand the interest, repayment schedule, fees, and consequences of late payment before accepting any loan offer.
A good borrowing decision begins with knowing what you are committing to.
After Receiving the Loan, Stick to the Plan
Getting the money is only the beginning. What happens next requires discipline.
If you borrowed to purchase inventory, use the funds for that purpose. If the loan was intended for equipment, make that investment rather than diverting the money to unrelated personal expenses.
It can be tempting to use some of the funds to settle personal needs, especially when other financial pressures exist. However, this can leave the business without the resources it needs to generate the income required for repayment.
Keep your business and personal finances separate, record how the money is spent, and monitor the results of the investment.
You should be able to look at your records and explain what the loan has helped your business achieve.
Don’t Assume Sales Will Automatically Cover Repayment
This is where many business owners need to pay closer attention.
Selling more does not always mean making more profit. You may sell out your inventory but still have outstanding supplier payments, delivery costs, staff expenses, and other obligations.
Your repayment plan should therefore be based on realistic cash flow, not optimistic sales projections.
Set money aside for repayments as revenue comes in. Avoid waiting until the repayment date before trying to find the funds.
And if you notice that your business is struggling financially, communicate with your lender early rather than ignoring the situation. Early communication gives both parties a better opportunity to understand the challenge and explore any available options.
Remember, Repayment Is Part of the Opportunity
A lending institution has a responsibility to assess applications carefully, communicate loan terms clearly, and treat borrowers fairly. Borrowers also have a responsibility to provide accurate information, use funds appropriately, and honour their repayment commitments.
When borrowers repay responsibly, funds can be made available to support other entrepreneurs who need them.
This is why repayment matters beyond the individual business owner. It contributes to a lending system that can continue serving more people.
At Shecluded, we believe women entrepreneurs deserve access to financing and the knowledge to use it effectively. Getting capital into the hands of women is important, but helping them build the financial discipline and business capacity to manage that capital is equally valuable.
Make Your Loan Work for You
Before applying for your next business loan, take an honest look at your business. Make sure you have a clear purpose for the funds, understand your repayment obligations, and have a realistic plan for generating the income needed to repay.
After receiving the money, remain disciplined, monitor your performance, and make decisions that protect the financial health of your business.
Remember, a loan is a financial commitment, not free money. Its real value is measured by what it helps your business achieve and your ability to repay it responsibly.
The goal is to grow your business, strengthen your finances, and remain in a position where you can access opportunities again when you need them.
Christine Ugwu